Choose an Insurance Quote
Cheap Edmonton Home Insurance Quotes
Save $300 or more on home insurance with Rates.ca.*
Compare home insurance quotes with other top providers in Edmonton



Jump straight to:
- Is home insurance getting more expensive in Edmonton in 2026?
- Edmonton home insurance premium trends 2024 – 2026
- How Edmonton’s biggest property risks compare to the rest of Alberta
- Edmonton’s biggest property risks by postal code
- Choosing the right home insurance policy in Edmonton
- Types of home insurance in Edmonton
- Add-ons to home insurance coverage in Edmonton
- What Edmonton home insurance may not cover
- Factors that affect your Edmonton home insurance premium
- How to get the cheapest home insurance in Edmonton
- Frequently asked questions about home insurance in Edmonton

Content Manager
Is home insurance getting more expensive in Edmonton in 2026?
Yes, home insurance is getting more expensive in Edmonton – as part of a broader Alberta-wide trend. According to the Applied Rating Index, home insurance premiums across the province rose 11.9% year over year in Q2 2026, with Edmonton homeowners feeling the same pressure as the rest of Alberta.
Key numbers: Edmonton home insurance
- Edmonton homes face the highest risk in two categories: system back-up (i.e., sewer back-up) and crime (theft).
- Crime (theft) poses extreme risk to homes across T5B and T5J postal codes.
- Homes that have postal codes starting with T5R postal code face extreme risk from system back-up.
- Rebuild costs in Alberta increased 24.3% between January 2021 and January 2026.
As of September 2026
Edmonton home insurance premium trends 2024 – 2026
Home insurance premiums in Alberta are on the rise in 2026, a trend Edmonton homeowners are seeing reflected in their own renewal notices, and one that’s on track to continue in 2027. According to the Applied Rate Index, premiums in Alberta increased 11.9% year over year in Q2 2026. This is above the comparable increase in Q2 2025, which was 9.5%, but well below the increase seen in Q1 2026, which was 16.2%. The overall trend, however, upward, as the four quarter have all seen year-over-year increases above the 10% mark in Alberta.
Note: The percentages listed above are derived from comparing rates from one quarter to the same quarter in the prior year (e.g., Q2 2026 is compared to Q2 2025).
Source: The Applied Rate Index (Q2 2026)
What's behind Edmonton's home premium increases in 2026?
As shown by a recent study by Statistics Canada, some of the biggest culprits behind the rise in home insurance premiums in Edmonton and Alberta at large are more frequent bouts of extreme weather in the last six years, plus higher rebuilding costs, which were in part caused by the pandemic.
So far, 2024 remains the costliest year on record for extreme weather claims, with insured losses exceeding $9.4 billion, according to the Insurance Bureau of Canada (IBC).
Edmonton has been at the centre of that trend this year. According to IBC's September 2026 summary of initial estimates from Catastrophe Indices and Quantification (CatIQ), the city recorded record rainfall in both June and July. A storm from May 31 to June 2 dropped more than a month's worth of rain on Edmonton in just a few days, flooding basements, roads and public spaces and causing over $80 million in insured losses. On June 20 and 21, another round of prolonged rainfall overwhelmed sewer systems in Edmonton and the surrounding area, causing over $160 million in insured losses. Edmonton then took the brunt of a July 10–11 outbreak of rain, hail and tornadoes that caused over $140 million in insured losses across Alberta and Saskatchewan.
As for rebuilding costs, a recent report by Verisk shows that residential rebuild costs in Alberta increased 24.3% between January 2021 and January 2026, with a 12.8% increase over the past three years. Canada is also short on skilled trades labour in the residential construction sector, with job vacancies being projected to rise from 11% to 13% per year between 2026 and 2045.
Though the outlook isn't exactly optimistic, there are ways to mitigate these issues – mainly through premium comparison and avoiding high-risk areas when buying a new home.
How Edmonton’s biggest property risks compare to the rest of Alberta
Rates.ca’s proprietary data shows that system back-up (i.e., sewer back-up) and crime (theft) pose the biggest risk to Edmonton homes in 2026. On the scale of Very Low, Low, Medium, Very High and Extreme, the system back-up and crime (theft) categories both fall under High. Wind/hail falls under Low, which is below the provincial median of Medium. Wildfire and flood from exterior sources also fall under Low, putting them on par with the rest of Alberta.
Edmonton’s biggest property risks by postal code
Rates.ca’s proprietary data shows that system back-up (i.e., sewer back-up) and crime (theft) pose the biggest risk to homes across most of Edmonton in 2026, aside from a few select postal codes. While several postal codes fall under Medium for crime (theft) risk, most fall under High. T5B and T5J fall under Extreme. T5R postal code also falls under Extreme in system back-up risk category, with most falling under High and the rest under Medium.
The other risk categories and postal codes do not exceed the median for Edmonton or Alberta at large.
How Rates.ca determines risk scores
Risk levels are ordered according to Forward Sortation Areas (FSAs) – the first three digits of a postal code and are based on proprietary data provided by a leading global insurance data, analytics, and technology provider.
To determine risks for individual cities and Alberta as a whole, we assigned a number to each risk score (e.g., Very Low became 1, Low became 2, etc.) and calculated a median.
Risk category breakdown:
- Wind/Hail: Included in a standard home policy.
- Crime (theft): Included in a standard home policy. However, certain valuable items often have set coverage limits (known as Special Limits). These items include jewellery, watches, luxury handbags or purses, furs and collectibles such as stamps, coins or sports cards. If you have such items, you might need to expand your coverage.
- Flood: System backup: Optional coverage that needs to be added separately.
- Flood: Exterior sources: Optional coverage that needs to be added separately.
- Wildfire: Included in a standard home policy as part of an overarching fire coverage.
Find the cheapest home insurance in Edmonton
Save money on Edmonton home insurance by comparing quotes from top Canadian insurers on Rates.ca. We aggregate quotes from more providers than anyone else, always finding you the best price.
Choosing the right home insurance policy in Edmonton
Residents of Edmonton are not required to take out home insurance by law, unlike car insurance. However, most lenders will require you to have home insurance if you intend to take out a mortgage. That’s while you’ll probably need it anyway!
There are many options for home insurance in Edmonton. The following list provides an example of what’s available.
Types of home insurance in Edmonton
Homeowners in Edmonton can choose from these three basic insurance plans:
- Basic: Also known as a ‘named perils’ policy, the basic home insurance package is generally the least expensive, as it offers the fewest benefits. Under a basic package, homes are usually protected against perils such as fire and wind.
- Broad: Sometimes called a ‘standard’ policy, the broad home insurance policy protects against most perils and may also include some of the contents of the home. Some perils may be listed as exclusions.
- Comprehensive: Often referred to as an ‘all-perils’ policy, the comprehensive policy provides protection against all perils and contents of the home.
What gets covered
- Property and building: As its name suggests, this policy provides coverage for structures on your property, including the land, from perils such as fire, theft, wind, water damage and more. Some policies require additional coverage for structures such as garages or sheds. It’s best to consult your Edmonton home insurance provider to make sure you are covered.
- Contents and personal property: Contents and personal property coverage protects your possessions, including furniture, clothing, electronics and houseware. More expensive items like fine art or jewellery would require additional coverage. Consult your Edmonton home insurance provider to find out what contents are covered in your policy.
- Additional living expenses: Should you be displaced from your home due to a claim resulting from damage or evacuation, additional living expenses will cover you for your temporary living costs, such as rent or food. Consult your home insurance provider for the costs and limits you are eligible for.
Liability coverage
- Personal liability: This protects you from liability or lawsuits resulting from someone getting injured on your property.
- Voluntary medical payments: Medical payments for someone who is injured or who you injure on your property will be covered under this policy. Generally, coverage is included for up to one year from the time of the accident.
- Voluntary property damage: This covers you should you unintentionally cause damage or loss to someone else’s property. It also covers minors under 12, who are under your care, and cause damage to another person’s property.
Add-ons to home insurance coverage in Edmonton
Besides basic, home and liability coverage, homeowners in Edmonton may want to make some additions. The following are some of the most common coverages offered by home insurance providers:
- Overland water: Not all home insurance providers offer this, but those that do provide coverage from overland water damage due to overflowing water from lakes, rivers or melting snow.
- Sewer back-up: This protects you from main sewer back-ups that cause damage to your home.
- Earthquake: This protects you from damage or losses caused by earthquakes. It is most useful in areas, like Western Canada, where earthquakes are more common.
- Mass evacuation: If a major event, like flooding or forest fires result in mass evacuations this will cover you for the living expenses you incur while living away from your home.
- Identity theft: In the 21st century identity theft is a real problem that can cause losses or damage. This coverage will pay for replacing documents such as your passport.
- Lock replacement: Theft or vandalism can cause damage to your locks. This coverage will help pay the replacement cost.
What Edmonton home insurance may not cover
Home insurance providers in Edmonton don’t cover every peril under a standard policy. Here are some of them:
- Renting all or part of your property to long- or short-term guests.
- Injuries or damage caused either intentionally or by illegal activity.
- Damage caused because basic measures of protection and maintenance have not been taken.
- Liability for clients or customers visiting a home-based business.
- Natural disasters, such as earthquakes and landslides.
- Certain water damage, such as sewer back-up and flooding from overland water.
- Certain weather issues in winter, such as damage to the outside of your home caused by freezing and water damage (due to frozen or burst pipes).
- Damage from insects and rodents.
How to get the cheapest home insurance in Edmonton
You can lower the cost of your home insurance premium in the following ways:
- Bundle auto and home: Some insurers may have a policy that bundles different types of insurance, like home and auto, allowing you to save money on both.
- Ask for discounts: See if you can get an alumni or professional membership discount from your insurer, such as a CAA or college/university alumni discount.
- Choose a higher deductible: You can choose a higher deductible to lower your home insurance premium. Most insurers in Edmonton will allow you to choose $500, $1,500 or $2,000 as your policy deductible.
- Upgrade your home: Home upgrades, like roof maintenance and replacing old plumbing, can lower your premium.
- Increase security: Installing a good security system minimizes the risk of theft, directly lowering your home insurance premium.
- Compare Edmonton home insurance quotes: Use quote comparison sites like Rates.ca to shop for the best home insurance quotes in just a few seconds.
How to get Edmonton home insurance quotes on Rates.ca
Tell us about your home
Answer a few basic questions about your home.
Compare your quotes
See quotes from top Canadian insurance companies side by side.
Choose the right coverage
Find the right protection for your home.
Secure your rate
Connect with the provider and secure your rate.
What people say about our quotes
Based on 7,167 reviews

Amazing
Amazing, informative and helpful customer service representative. Great pricing and great service.
Elaine Smith
Great customer service
Great customer service
Vera Trifanova
A little long of a call 45 min total…
A little long of a call 45 min total however I got a good price on both auto and home insurance so it was worth the wait. Thank you Ryan
Julian Langiano
Very straight forward.
Very straight forward.
Brandon Sutherland
I had a great experience with Rates.ca
I had a great experience with Rates.ca! The representative Shanal Kajar was professional, friendly, and explained everything clearly, making the whole process easy to understand. Excellent customer service and a smooth experience. Highly recommended!
Said Ahmad Farid Ghazanfari
The representatives were very efficient.
The representatives were very efficient.
Isaac
Patient caring agents
Patient caring agents
John Cousins
Excellent service.
Excellent service.
Andrew Quenneville
Fast and easy to choose from the…
Fast and easy to choose from the options available.
Abhinand
Frequently asked questions about home insurance in Edmonton
Here’s everything you may be wondering about home insurance coverage in Edmonton.
Which company offers the cheapest Edmonton home insurance?
No single home insurance company offers the cheapest rate for every property. Insurers assess risk differently, so one may offer the cheapest rate for one home but not another. If you’re looking for a cheap home insurance plan, comparison shopping will help you find the best home insurance quotes from top Edmonton insurers.
What risks do homeowners face in Edmonton?
While Edmonton homes face a low risk from wildfire damage, they are prone to the following perils:
- Internal water damage from burst pipes: During the winter months, low temperatures increase the risk of water damage from burst pipes. Given how cold the winter gets in Edmonton, this is a common issue.
- Sewage back-up: An aging sewer system or melting snow can cause a sewer backup. Damage as a result of sewer backup may be covered by your policy, or will be available as an add-on. Many insurers offer different amounts of sewer backup coverage. Ask your insurer for more information.
- Overland water: Rainstorms and melting snow can cause overland flooding and heavily damage your home. Overland water insurance may be an optional add-on, making it important for you to ask your insurer about the details of your coverage options.
How much insurance coverage do I need for my home in Edmonton?
Each individual homeowner is different. You may have a lot of expensive items in your home, or you may live in an area that has a higher crime rate. Everyone’s needs vary. It’s best to seek out the cheapest rates on Rates.ca where you can compare quotes from several providers. Once you have your rate range, talk to one of our specialists, or a broker, who can advise on the best policy for you.
What is a loss settlement option in home insurance?
If an expensive item that you own is damaged or stolen, the insurance company may not necessarily pay you the exact amount of money you paid for it at the store.
A loss settlement refers to how insurers decide the amount you will receive after you suffer a loss to an insured item. Differences in coverage will mean differences in the amount paid for the same item depending on the option you choose. There are two loss settlement options:
- Replacements cost. The replacement cost takes into account the cost of replacing a damaged asset at today’s cost – i.e the insurance company pays you the same amount you would pay to buy that same item today.
- Actual cash value. The actual cash value (also known as the ‘market value’) loss settlement option is determined by the current value (worth) of your property, not how much it would cost to replace it with a brand new one.
Is fire covered under my Edmonton home insurance policy?
The amount of coverage you need will be determined by factors such as the value of your home and contents, the location and age of the home, and the risk you pose to the insurer. Home insurance policies typically offer three or more types of coverage, including dwelling, contents and personal liability. Common risks like fire and theft are typically covered by standard policies, but you may have unique needs or valuables that require extra coverage. Check with your insurance agent or broker to make sure you have enough coverage.

Taras Trofimov, Content Manager
Taras has over nine years of content marketing experience across multiple industries in B2B and B2C spaces. He has produced thought leadership content for organizations like Constellation Software, Facebook and Yellow Pages as well as outlets like Huffington Post and MSN Canada.
He graduated from York University with a Bachelor of Arts degree and studied Technical Communication at Seneca College.
Latest home insurance articles:
Shopping for cheaper home insurance isn't tied to a calendar but aligns best with your changing needs and a market that's constantly shifting.
When subletting your rental property remember to inform your insurer. Your subtenant should carry their own insurance policy.
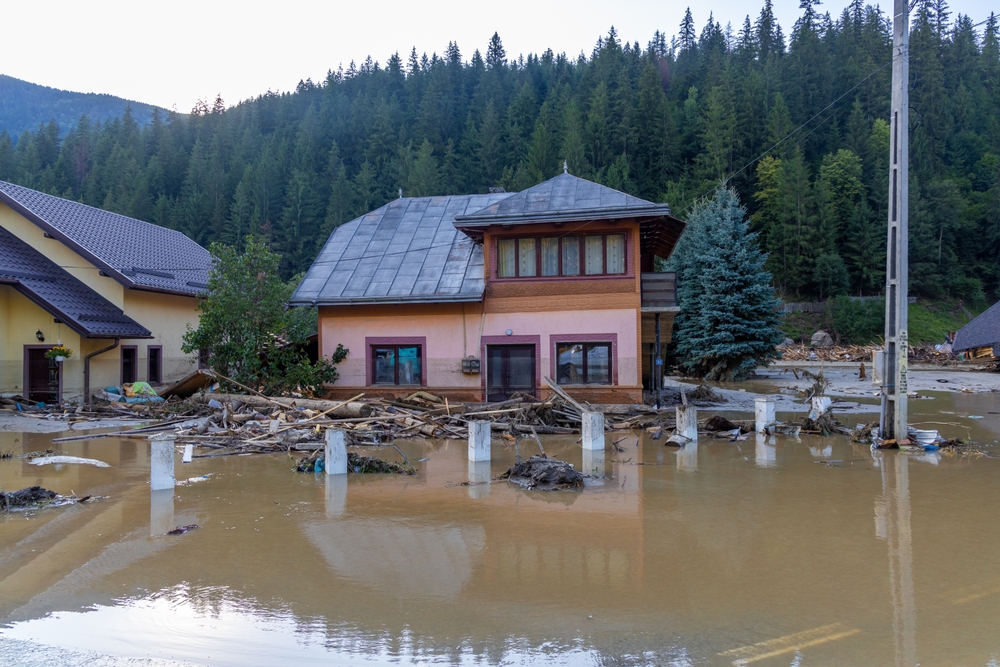
A heavily discounted home with prior flooding seems attractive, but unexpected repair costs can erase savings.
As the real estate market fluctuates, doing minor, strategic renovations may help improve your home equity and offset falling home values.
A comprehensive home insurance policy can help you cover significant repair costs from a water-damaged basement.
How to reduce risk of your car getting caught in an underground parking garage flood and details on your insurance coverage options.
Find more great home insurance rates
Disclaimer
*More than 50% of Rates.ca users in Canada who obtained a home insurance quote from January to December 2025 saw savings ranging from $50 to $750, with an average savings of $367.52. The average savings amount represents the difference between the users’ average lowest quoted premium and the average of the second and third lowest quoted premiums generated by Rates.ca.